FREE NEWSLETTER

I TURNED AGE 64 over the Labor Day weekend. One of my goals for my 65th orbit of the sun is to really dig into Medicare.
Luckily, I have a few friends and relatives who have blazed the trail before me. I’ve also studied Medicare as part of some financial planning courses I took a few years ago. Still, one topic I’ve never researched in detail is Medicare’s income-related monthly adjustment amount, otherwise known as IRMAA.
Traditional Medicare is made up of Part A (hospitalization), Part B (doctor’s services, outpatient costs and medical equipment) and Part D (prescription drugs). Parts B and D have monthly premiums. For 2021, the Part B standard monthly premium is $148.50. Part B also has a $203 deductible. After you meet your deductible, Medicare typically covers 80% of your Part B costs. Meanwhile, the Part D standard monthly premium varies based on the plan you choose.
IRMAA is an amount you may pay in addition to your standard Part B and Part D premiums—if your income is above a certain level. The Social Security Administration has a series of income brackets that determine what that amount is. Most people will pay just the standard premium amount. But if your modified adjusted gross income is above the specified threshold, you may owe IRMAA.
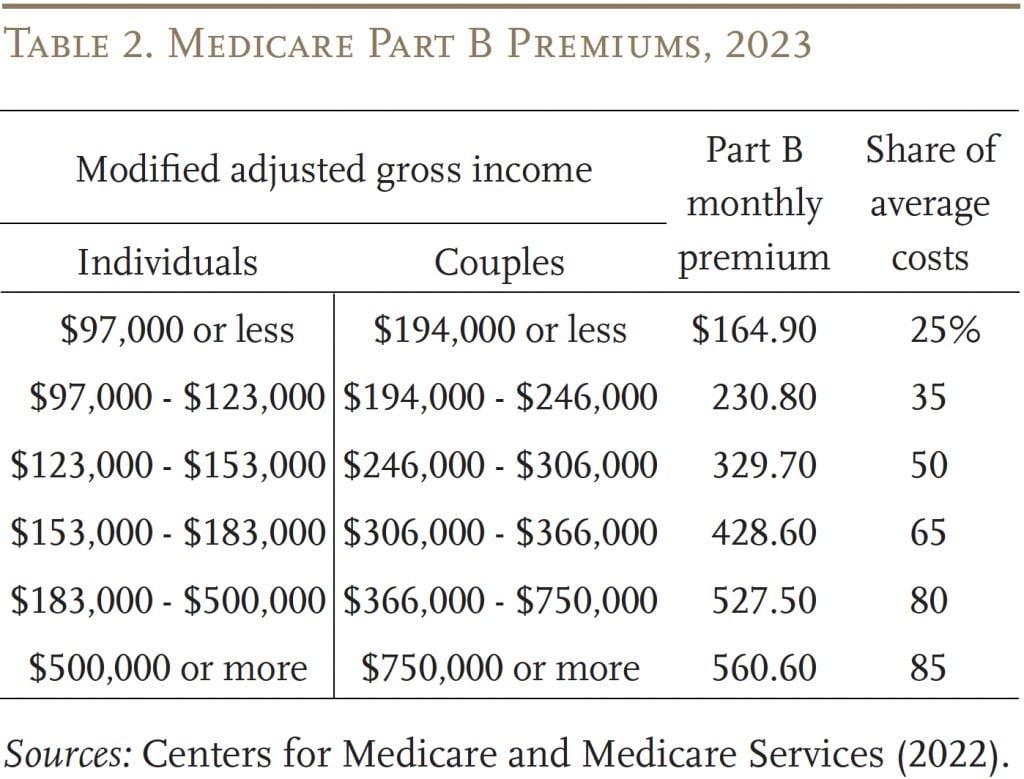
You can review 2021’s Part B monthly premiums by heading here. The IRMAA increase for Part B starts at incomes above $88,000 for single filers and $176,000 for joint filers. The surcharge for Part B can take your 2021 premium from $148.50 to $207.90—and perhaps as high as $504.90. The increase is per person, so married couples are looking at double these amounts. Meanwhile, the IRMAA surcharge for Part D starts at $12.30 a month and increases to $77.10 at the top income bracket. The Part D surcharge uses the same income brackets as those used for Part B. You can review the Part D amounts here.
When you sign up for Medicare, you’re provided with an initial determination of your costs, including whether you’ll have to pay IRMAA. The premium surcharge is usually based on your income from two years earlier, so 2021’s surcharges are based on your 2019 modified adjusted gross income. If it’s determined your income is above the threshold, you’ll be sent a notice explaining IRMAA in detail.
A friend of mine enrolled in Medicare this summer. Although he retired from fulltime work four years ago, he still does some part-time consulting. His consulting income for 2019 was high, so his modified adjusted gross income for that year was also high, especially for a single filer. His initial determination showed that his monthly Part B premium for 2021 would be $475.20, an increase of $326.70 a month—equal to $3,920.40 a year—over the standard premium.
He was concerned because 2019 was an outlier, unlikely ever to be matched again. Due to COVID-19, he had very little consulting income in 2020, and 2021 looks to be a slow year also. He doesn’t intend to ever work as many hours as he did in 2019. Basing his IRMAA on 2019’s income struck him as unfair.
His initial determination notice explained Medicare’s process to appeal if he thought his IRMAA surcharge was unfair. My friend claimed a life-changing event. In his case, the event was a work reduction. Other acceptable life-changing events include marriage, divorce, death of a spouse and loss of a job. He filled out Form SSA-44, and requested a letter from his employer describing the reduction in work and providing an estimate of his 2021 income. He then submitted these documents to the Social Security Administration. Within a few weeks, Social Security responded, reducing his IRMAA surcharge. IRMAA is recalculated each year. For my friend, Social Security will use his 2021 estimated income to calculate 2022’s IRMAA surcharge and then, for 2023, use his actual 2021 tax return.
As my friend’s situation makes clear, avoiding large IRMAA surcharges is another of the tax topics that retirees need to consider. Your modified adjusted gross income is determined by taking your adjusted gross income from your tax return, and adding back any tax-exempt foreign income and any tax-exempt interest. In my friend’s case, he now knows how much he can work to stay in a lower IRMAA bracket. Doing things to reduce your modified adjusted gross income, such as qualified charitable distributions in your 70s or later and Roth conversions in your 50s, can help reduce your taxable income during retirement, possibly allowing you to avoid IRMAA.
Be careful with those Roth conversions. Many folks use their early retirement years to covert part of their traditional IRA to a Roth. But if you’re in the tax year that includes your 63rd birthday and hence you’re two years from starting Medicare, a Roth conversion could lead to steep IRMAA surcharges. Also keep in mind that IRMAA is a so-called cliff penalty—meaning that, if you move up to a higher bracket by just $1, you’ll be hit with the full amount of the higher surcharge.
 Richard Connor is a semi-retired aerospace engineer with a keen interest in finance. He enjoys a wide variety of other interests, including chasing grandkids, space, sports, travel, winemaking and reading. Follow Rick on Twitter @RConnor609 and check out his earlier articles.
Want to receive our weekly newsletter? Sign up now. How about our daily alert about the site's latest posts? Join the list.
One of the shocks I experienced from IRMAA was not my fault. The SSA calculated my IRMAA back in the middle of the COVID lockdowns, and then a year later came back and said that it had not had current information at the time and had updated the IRMAA calculation. They informed me that I was being dinged for a large deficiency. But the real shock was that the SSA letter said that my Social Security payment would be docked 100% effective immediately, and I would continue to receive $0 – nada – until the entire deficiency was made up. That took a few months. I could muddle through, but it seems to me that the process is punitive. The SSA should allow Social Security recipients to continue to still have some portion of their monthly payment sent to them while an IRMAA deficiency (remember, not caused by them) is eliminated. (It certainly does not seem controversial, and would rank at about a 2 on the 10-point college student loan forgiveness meter.)
This is a helpful chart to explain how Part B is paid for:
 .webp