FREE NEWSLETTER

There’s nothing wrong with spending money—as long as it’s spent on things that deliver plenty of happiness.
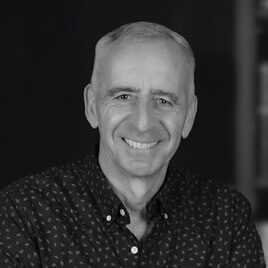 After spending more than two decades building a successful landscaping business with his twin brother Nicholas, Andrew Clements retired in 2015 with a new appreciation for what matters most. Born in England, his essays draw on a life that has included growing up in England and Bangladesh, entrepreneurship, caregiving, family loss and travel. A regular HumbleDollar contributor, he enjoys tellingstories that remind readers life’s richest lessons often have little to do with money. Andrew is the older brother of HumbleDollar founder Jonathan Clements, whose life and legacy have inspired some of his most personal writing. He lives in Florida with his husband, Joey.
 Adam M. Grossman is the founder of Mayport, a fixed-fee wealth management firm. Sign up for Adam's Daily Ideas email, follow him on X @AdamMGrossman and check out his earlier articles.
IBTG (2026) through IBTK (2030+)IBDR (2026) through IBDV (2030+)IBHE (2026) through IBHG (2028+)BSGR (2027), BSTS (2028), etc.BSCQ (2026) through BSCZ (2035+)BSJQ (2026) through BSJY (2034)BSMQ (2026) through BSMZ (2035+)MYCF (2026) through MYCO (2035)MYHA (2027) through MYHE (2031)MYMF (2026) through MYMK (2031)VBCA (2027) through VBCJ (2036)NO. 53: STRIVING toward our goals is usually more satisfying than achieving them. Yes, we should think hard about our goals—but we should also ask whether we’ll enjoy the journey.
NO. 37: WE ATTRIBUTE our winners to our own brilliance, a phenomenon known as self-attribution bias. Meanwhile, we blame our losers on others—the neighbor, financial advisor or TV pundit who suggested the investment. This makes it harder to learn from our mistakes, while boosting our self-confidence and increasing the risk of future missteps.
MAKE END-OF-LIFE decisions. Ponder who should make medical and financial choices for you if you’re incapacitated. Draw up powers of attorney that reflect those wishes. Add a living will, detailing what life-prolonging medical procedures you want taken. Decide whether to donate your organs. Specify what sort of funeral you want. Choose an executor.
DICTATOR GAME. In experiments, a “dictator” is given money or some other prize and gets to decide how to split it with another person. If a dictator’s goal was maximum financial gain, he or she wouldn’t give anything. But in experiments, dictators typically share part of the prize, suggesting they’re concerned with fairness and perhaps with how they’re perceived.

NO. 53: STRIVING toward our goals is usually more satisfying than achieving them. Yes, we should think hard about our goals—but we should also ask whether we’ll enjoy the journey.
WHAT WAS MY DAD thinking when he asked me to help him and my mom with their finances? Did he expect me to give him money? Maybe.
Up until that moment, my dad handled the family finances. Both he and Mom were retired, though my mom still worked occasionally as an adjunct professor. My mom assumed things were okay, though I had my suspicions.
One day, I saw a credit card bill that showed a large outstanding balance,
IF YOU PUT DOWN less than 20% on a conventional home loan and you’re still paying private mortgage insurance (PMI), do what I did: See if you can get those pesky PMI payments eliminated.
I purchased a home in September 2017 for $341,000. The interest rate was near 4% and I put down roughly 10%. Why not put down 20%, so I could avoid PMI? My thought: If I can borrow money at an interest rate below 5% and get a reasonable rate of return elsewhere,
THE HIGHEST CREDIT score possible is 850, and I’ve hit that mark in eight of the past 12 months. In the other four months, I had a score of either 844 or 846 under the credit rating formula created by FICO, formerly called Fair Isaac Corp.
A FICO score between 800 and 850 is considered exceptional and gets you the best rates on loans. A score of 670 or more is considered “good,” but more doors and opportunities are available when your score hits 740,
ACCORDING TO MY local newspaper, the average home price in my town rose 450% over the past 25 years. That made me ponder how I could use my home equity to fund my desired retirement lifestyle. I’m certainly not alone in thinking this way.
There are three ways you can access home equity. You can sell your home and downsize, you can take out a home equity line of credit or you can take out a reverse mortgage.
FAMILY CAN BE A wonderful asset. Your parents, siblings and adult children might help with home repairs, offer free advice based on their professional expertise and take care of the dog while you’re on vacation.
When the circumstances are right, I think there’s an opportunity to take this even further. For instance, earlier this year, I provided my daughter with a private mortgage, which allowed her to purchase her first home. There aren’t many people I’d strike that deal with,
THE GREAT RECESSION highlighted the frightening amount of debt—especially mortgage debt—that had been taken on by many American families.
A decade later, the picture is far brighter, with one exception: student loans. Since 2008’s third quarter, education debt has ballooned 144%, according to data just released by the Federal Reserve Bank of New York. But the total of all other debt—mortgages, car loans and credit card balances—is up less than 1% over the same period.



My Favorite Room
DAN SMITH | Sep 17, 2026
Flipping the Script on Asset Allocation?
Mark Crothers | Sep 18, 2026
The Jonathan I Found: Through Others’ Eyes
ArticleAndrew Clements | Sep 19, 2026
When $2000 Isn’t Worth the Hassle
Mark Crothers | Sep 16, 2026
Little luxuries
greg_j_tomamichel | Sep 19, 2026
Is a Roth conversion an optimal strategy in my situation?
batperson | Sep 12, 2026
Structuring Bonds
ArticleAdam M. Grossman | Sep 19, 2026
Target Maturity Bond Funds
DAN SMITH | Sep 18, 2026
- Market Status: The market leader and pioneer in target-maturity bond ETFs.
- Product Lineup: Covers virtually every major sector of fixed income with annual maturity dates running up to 10+ years out.
- Asset Classes Offered:
- U.S. Treasuries:
- Investment Grade Corporates:
- High Yield Corporates:
- Municipal Bonds: Extensive national and state-specific (e.g., California, New York) muni suites.
- TIPS (Inflation-Protected): Target-date Treasury Inflation-Protected Securities.
2. Invesco (Invesco BulletShares)IBTG(2026) throughIBTK(2030+)IBDR(2026) throughIBDV(2030+)IBHE(2026) throughIBHG(2028+)- Market Status: The second major pillar of the space, boasting large liquidity and long historical track records.
- Product Lineup: Robust annual maturity lineups running through 2035 and beyond.
- Asset Classes Offered:
- U.S. Treasuries:
- Investment Grade Corporates:
- High Yield Corporates:
- Municipal Bonds:
3. State Street Global Advisors (SPDR MyIncome / SSGA My20XX)BSGR(2027),BSTS(2028), etc.BSCQ(2026) throughBSCZ(2035+)BSJQ(2026) throughBSJY(2034)BSMQ(2026) throughBSMZ(2035+)- Market Status: A newer entrant that distinguished itself by offering actively managed target-maturity ETFs (rather than purely passive index trackers).
- Product Lineup: Focuses on active credit selection to optimize yield and reduce cash drag during the maturity year.
- Asset Classes Offered:
- Corporate Bonds:
- High Yield Corporates:
- Municipal Bonds:
4. Vanguard (Target Maturity Corporate Bond ETFs)MYCF(2026) throughMYCO(2035)MYHA(2027) throughMYHE(2031)MYMF(2026) throughMYMK(2031)- Market Status: Entered the target-maturity landscape with low-cost index options.
- Product Lineup: Focuses on investment-grade corporate bonds with explicit target years.
- Asset Classes Offered:
- Corporate Investment Grade:
"VBCA(2027) throughVBCJ(2036)The Ultimate Tail Risk
Mark Gardner | Sep 13, 2026
I will still take the dividends
R Quinn | Sep 12, 2026
The Silent Committee
John Goodell | Sep 14, 2026
The $5,000 Thought Experiment
Mark Crothers | Sep 10, 2026