
FREE NEWSLETTER

Another year passes and still there are no inductees to the market-timing hall of fame.

Latest PostsAll Discussions »

Retirement

Will Congress Wait Until the Last Minute on Social Security?

"The night before, obviously. Don't you know what Congress is like? Then they'll congratulate themselves on a great job."
- Ormode
Read more »

Spending

Anyone For S.K.I.ing?

"With no children to inherit my money, my preference is to support other people's children. By donating to charities targeting underprivileged youth. Thanks for asking."
- Hall Plante
Read more »

Spending

Little luxuries

"new socks, I love the feel of a new sock...not changing new socks every week....but maybe more often than my current default of, no hole, keep going...love the article"
- Roy Rover
Read more »

Health

My Name is Dan, and I’m a CPAP User

"I am 50 and started CPAP 3yrs ago. I use nasal pillows. I tried everything else and did not like it. All I can say is - keep trying - you will get there. it is difficult. I was lucky. I took to CPAP like a duck to water. 1 week adjustment period only, I had an amazing sleep therapist who helped me through it, she gave me exercises and tips to make it easier to transition to using it. All the best. I can honestly say, my life is SO much better for it."
- Roy Rover
Read more »

From HumbleDollar Founder Jonathan Clements
Lists

Why HumbleDollar?

IN OUR 20s, WE TEND to be a confident lot: We figure we know what we want from our life, that the goal is…
Read more »

In Retirement

Widow’s Penalty Redux

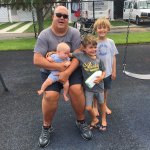
A RECENT post by achnk53 about the impact of a spouse’s death on the survivor’s taxes piqued my interest.  The post referenced an interesting Kiplinger article about the “Widow’s Penalty”, or the negative tax implications on a surviving spouse after the death of a spouse. A surviving spouse can file Married Filing Jointly (MFJ) in the year of their spouse’s death. In the full year following the spouse’s death you must file Single.  There are some beneficial filing rules for surviving spouses who have dependent children, but that is beyond this post. Nine days later John Urban published an article running the tax numbers for 3 different retiree scenarios, and using the data to provide some excellent suggestions for readers.  In between these two articles I had run some similar case studies to understand the impacts. I ran some case studies using the 2026 Dinkytown 1040 Calculator.  I considered a “lower" income retired couple.   The impact of one spouse passing is very dependent on the sources of income. Assume the retired couple were each receiving $36,000 in annual SS benefits. They have no other sources of income.  The couple filing jointly would have no taxable income, and no tax for 2026.  Had the husband died in 2025, the surviving widow would have seen her income reduced to $36,000. If she needed the lost income, and found a job that paid $36,000, her income would match the original $72,000. But $21,500 of her SS benefit would be taxable, her taxable income would be $33,350, and her annual tax bill would be $3,757.  The table below shows the details of this analysis: Tax Calculation After accounting for the reduction in Medicare related spending, she has similar spending power. But she had to go back to work to achieve that.  This, and the previous examples, reinforce the importance of understanding a couple’s financial details before and after the passing of a spouse. Income will likely be reduced, but expenses may also be reduced. Lower income retirees who depend primarily on both partners SS benefits may see the biggest impact. I also ran a comparison of our tax return for 2026, for both MFJ and if my wife filed single.  I assumed our income consisted of my pension, my wife’s SS benefit, and my SS benefit had I claimed it on January 1, 2026. When I die my wife will receive 75% of my pension, and my higher SS benefit.  The results were not surprising.
  • Her total income would be 68% of our combined pre-death income.
  • Her annual tax bill would be $1,250 more than our joint tax bill.
  • Her effective tax rate would increase by 4.2%.
  • 85% of her SS benefits would be taxable
  • Her spendable income after taxes would be about 65% of the joint amount.
  • She would lose about 20% of the new Senior Deduction
  • She would have no NJ State Tax liability
I then ran an additional scenario with the same assumptions, but also assuming we were 4 years older and would both have to take initial RMDs in 2026.  This scenario reflects one of the concerns frequently expressed when discussing this topic – what happens when the surviving spouse is responsible for reporting the income from both RMDs on her Single tax return. The results changed to reflect the scenario. 
  • Her total income would be about 79% of our combined pre-death income.
  • Her annual tax would be $708 more than the joint tax filing.
  • Her effective tax rate would increase by 3.8%.
  • Her spendable income after taxes would be about 80% of the joint amount.
  • She would lose all of the new Senior Deduction.
  • Her NJ State Income tax would be $540 more than the joint tax filing.
  • She would be pushed up one IRMAA bracket in 2028.
These results are a simplified look at our finances today.  My pension and my wife’s SS benefit cover our non-discretionary, and a decent portion of our discretionary, expenses. The wild card is travel – how much we spend in any year is our choice and may require additional income. I’m about 11 months from claiming my SS benefit, at which point virtually all of our expenses will be covered in a fairly tax-efficient way.  RMDs are still 4 years away. This was a good exercise to get a feel of how my demise would impact my wife’s finances. It would have some financial impacts, but I believe our plan can handle them. I’m considering running some more detailed projections varying the age at death to assess the impacts, but a quick look made me reasonably confident our retirement savings will be adequate, even considering long term care. I will also continue to look at Roth conversions each year.   Richard Connor is a semi-retired aerospace engineer with a keen interest in finance. He enjoys a wide variety of other interests, including chasing grandkids, space, sports, travel, winemaking and reading. Follow Rick on Twitter @RConnor609 and check out his earlier articles.
Read more »

Investing

Financial Lessons

WHAT'S THE MOST important idea in personal finance? It’s hard to single out just one, but over the years, I’ve found the following dozen ideas to be among the most useful.
  1. Whether it’s on TV or online, there’s never any shortage of market prognosticators. Especially during a bull market, everyone seems to have an opinion on where things are headed. The reality, though, is that people can only guess about how the economy, the market or any individual investment will perform. Convincing as they might sound, no one has a crystal ball. That’s why, when it comes to investing, I suggest taking an evidence-based approach, one that relies as much as possible on data and research rather than on the simple stories, anecdotes and sayings that are so prevalent among market commentators.
  2. What does the data tell us? Among the most significant research in recent years is the work of Hendrik Bessembinder. In looking at the historical returns of stocks, he found that just a tiny fraction—only 4%—have accounted for the vast majority of the market’s gains over and above what Treasury bills paid, and the median stock actually delivered a negative return. This is one of the key reasons I recommend index funds rather than picking individual stocks or investing in an actively-managed fund. Identifying that 4% is almost impossibly difficult. But if you invest in a broad-based index fund, you’ll have a high likelihood of owning the next Apple or Nvidia.
  3. Be careful not to miss the forest for the trees. The most important driver of investment risk and return for most people, most of the time, is asset allocation. In other words, the dollars you have in stocks vs. in bonds or in cash will almost always be the most consequential decision. It’s easy to lose sight of that, though, because so much of the investment commentary from day to day focuses on details like small differences in fund expenses or small differences in bond yields. To be sure, details can be important, but only after considering the big picture.
  4. Another challenge in investing is that certain rules of thumb gain so much popularity that they end up being seen as rules rather than just guidelines. For example, some say that the percentage of a portfolio allocated to bonds should be equal to an investor’s age. To me, that’s illogical. Consider Bill Gates. He’s 70 years old, but it stands to reason that he shouldn’t have the same asset allocation as any other 70-year-old. Rules of thumb are useful as points of reference, but we shouldn’t lose sight of the fact that everyone’s situation is different, and our investments should reflect that. More to the point, don’t worry if you’re doing something different from the next person.
  5. Buy insurance, but only to protect against losses you couldn’t absorb on your own. What does this mean in practice? In many cases, it’s possible to significantly cut insurance premiums by increasing deductibles. For example, if you have a seven-figure net worth, you might consider raising the deductible on your homeowner’s insurance to $5,000 or $10,000 or even more. Similarly, you might re-evaluate your life insurance as your net worth grows. You’ll likely become “self-insured” at some point, and then you could reduce or drop that coverage.
  6. Personal finance is quantitative, but we should never make decisions based only on the numbers. For example, a common question is how much cash to keep on hand. While we could work out an optimal number on a calculator, that shouldn’t be the final answer. You should also consider what would provide you with peace of mind. That is equally important.
  7. Be wary of the psychological pitfall known as recency bias. This is the tendency to extrapolate from recent experience and to downplay the possibility that things might change. The most famous example? In the late-1920s, when the stock market was booming, Yale University economist Irving Fisher declared that the stock market had reached a “permanently high plateau.” Just nine days later, the market crashed, ultimately dropping 89% from its peak.
  8. Avoid high fees. The research firm Morningstar once wrote, “If there’s anything in the whole world of mutual funds that you can take to the bank, it’s that expense ratios help you make better decisions. In every single time period and data point tested, low-cost funds beat high-cost funds.”
  9. Keep things simple. Most importantly, I would be wary of investments that aren’t easily understood. Not only can this help keep investment costs down, but it also makes it much easier to monitor your financial picture. Legendary fund manager Peter Lynch said it best: “Never invest in any idea you can't illustrate with a crayon.”
  10. Avoid “interesting” investments. So far this year, Wall Street has introduced more than 1,000 new exchange-traded funds (ETFs). How many of these are worth your attention? My guess is you could probably count them on one hand. More than 80% of these new funds are actively-managed, and more than 30% employ leverage. And there are more to come. Fund companies recently filed paperwork to create ETFs that will track the performance of major league sports teams. They won’t actually own shares in the teams; instead, they’re expected to rise and fall in response to each team’s wins and losses.
  11. For years, I’ve argued that bitcoin isn’t a valid investment. Even though it’s gone way up since I first made that argument, I still feel the same way, and for the same reason: because it lacks intrinsic value. Unlike stocks or bonds, it doesn’t generate any dividends or interest. Bitcoin’s price is not anchored to anything measurable or tangible, and that’s why, in my opinion, its price is so volatile.
  12. When it comes to investment risk, investors’ attention usually turns to the stock market. That makes sense, but as we’ve seen this year, bonds are not without risk. And unfortunately, the total-bond market index, which is often seen as the simplest, set-it-and-forget-it option, is one that carries quite a bit of risk. If you’re choosing bond investments, my recommendation is to pay attention to a metric known as duration. This tells you how sensitive a bond, or bond fund, will be to interest rate changes. In my view, investors should hold a sizable portion of their bond investments in a fund, or in individual bonds, with a duration of less than two years.
Adam M. Grossman is the founder of Mayport, a fixed-fee wealth management firm. Sign up for Adam's Daily Ideas email, follow him on X @AdamMGrossman and check out his earlier articles.
Read more »

Behavior

The Art of Making Do

"Ed, I was caught like a naughty child beside that trash bin — in hindsight, it's quite an amusing image. As for your suspicion, you're entirely correct. There's real satisfaction in making do, not out of hardship, but as a lightly worn badge of honour to my frugal philosophy. On the matter of your garden fork, I took the opposite approach. Mine's a fine stainless steel piece, with the shaft and handle carved from a single piece of wood. It's a wonderful tool to look at, and I always enjoy handling it… the actual forking, less so."
- Mark Crothers
Read more »

Behavior

Time Is Priceless

"Mark, that’s an excellent point. We certainly don’t have to wait until retirement to recognize the value of our time. Looking back, I wish I had understood that as clearly as you did when your children were still at home. I spent too many years focused on building a business and providing for my family, sometimes at the expense of simply being present. I like your motto, “Use money, love people.” Money is a tool. The people we share our lives with are what give that tool a purpose. Thanks, Mark."
- Andrew Clements
Read more »

In Retirement

Keep an eye on Medigap policies

"I personally would not consider a MA plan, unless it was a "flavor" of MA sponsored by a former employer (offering retiree medical) which may offer the full network of medical providers offered by Original Medicare. Most "over the counter" MA plans offered to the general public have network restrictions to PCP and specialists which can be an eye opener when starting to lean heavily on coverage for a serious medical condition. It seems like you have a fairly generous plan for out of state health needs- most do not offer that type of coverage, as when you are away from your home network, benefits are usually somewhat limited."
- Bill C
Read more »

Taxes

Shouldn’t property taxes be a realistic part of retirement planning? Sorry, I think this is a major financial and social issue.

"At this time, income taxes are regressive. Wealthy people take far too many deductions. The top rate is too low. And Social Security taxes shouldn't be capped below $1M."
- Cammer Michael
Read more »

Retirement

Will Congress Wait Until the Last Minute on Social Security?

"The night before, obviously. Don't you know what Congress is like? Then they'll congratulate themselves on a great job."
- Ormode
Read more »

Spending

Anyone For S.K.I.ing?

"With no children to inherit my money, my preference is to support other people's children. By donating to charities targeting underprivileged youth. Thanks for asking."
- Hall Plante
Read more »

Spending

Little luxuries

"new socks, I love the feel of a new sock...not changing new socks every week....but maybe more often than my current default of, no hole, keep going...love the article"
- Roy Rover
Read more »

Health

My Name is Dan, and I’m a CPAP User

"I am 50 and started CPAP 3yrs ago. I use nasal pillows. I tried everything else and did not like it. All I can say is - keep trying - you will get there. it is difficult. I was lucky. I took to CPAP like a duck to water. 1 week adjustment period only, I had an amazing sleep therapist who helped me through it, she gave me exercises and tips to make it easier to transition to using it. All the best. I can honestly say, my life is SO much better for it."
- Roy Rover
Read more »

From HumbleDollar Founder Jonathan Clements

Lists

Why HumbleDollar?

IN OUR 20s, WE TEND to be a confident lot: We figure we know what we want from our life, that the goal is…
Read more »

In Retirement

Widow’s Penalty Redux

A RECENT post by achnk53 about the impact of a spouse’s death on the survivor’s taxes piqued my interest.  The post referenced an interesting Kiplinger article about the “Widow’s Penalty”, or the negative tax implications on a surviving spouse after the death of a spouse. A surviving spouse can file Married Filing Jointly (MFJ) in the year of their spouse’s death. In the full year following the spouse’s death you must file Single.  There are some beneficial filing rules for surviving spouses who have dependent children, but that is beyond this post. Nine days later John Urban published an article running the tax numbers for 3 different retiree scenarios, and using the data to provide some excellent suggestions for readers.  In between these two articles I had run some similar case studies to understand the impacts. I ran some case studies using the 2026 Dinkytown 1040 Calculator.  I considered a “lower" income retired couple.   The impact of one spouse passing is very dependent on the sources of income. Assume the retired couple were each receiving $36,000 in annual SS benefits. They have no other sources of income.  The couple filing jointly would have no taxable income, and no tax for 2026.  Had the husband died in 2025, the surviving widow would have seen her income reduced to $36,000. If she needed the lost income, and found a job that paid $36,000, her income would match the original $72,000. But $21,500 of her SS benefit would be taxable, her taxable income would be $33,350, and her annual tax bill would be $3,757.  The table below shows the details of this analysis: Tax Calculation After accounting for the reduction in Medicare related spending, she has similar spending power. But she had to go back to work to achieve that.  This, and the previous examples, reinforce the importance of understanding a couple’s financial details before and after the passing of a spouse. Income will likely be reduced, but expenses may also be reduced. Lower income retirees who depend primarily on both partners SS benefits may see the biggest impact. I also ran a comparison of our tax return for 2026, for both MFJ and if my wife filed single.  I assumed our income consisted of my pension, my wife’s SS benefit, and my SS benefit had I claimed it on January 1, 2026. When I die my wife will receive 75% of my pension, and my higher SS benefit.  The results were not surprising.
  • Her total income would be 68% of our combined pre-death income.
  • Her annual tax bill would be $1,250 more than our joint tax bill.
  • Her effective tax rate would increase by 4.2%.
  • 85% of her SS benefits would be taxable
  • Her spendable income after taxes would be about 65% of the joint amount.
  • She would lose about 20% of the new Senior Deduction
  • She would have no NJ State Tax liability
I then ran an additional scenario with the same assumptions, but also assuming we were 4 years older and would both have to take initial RMDs in 2026.  This scenario reflects one of the concerns frequently expressed when discussing this topic – what happens when the surviving spouse is responsible for reporting the income from both RMDs on her Single tax return. The results changed to reflect the scenario. 
  • Her total income would be about 79% of our combined pre-death income.
  • Her annual tax would be $708 more than the joint tax filing.
  • Her effective tax rate would increase by 3.8%.
  • Her spendable income after taxes would be about 80% of the joint amount.
  • She would lose all of the new Senior Deduction.
  • Her NJ State Income tax would be $540 more than the joint tax filing.
  • She would be pushed up one IRMAA bracket in 2028.
These results are a simplified look at our finances today.  My pension and my wife’s SS benefit cover our non-discretionary, and a decent portion of our discretionary, expenses. The wild card is travel – how much we spend in any year is our choice and may require additional income. I’m about 11 months from claiming my SS benefit, at which point virtually all of our expenses will be covered in a fairly tax-efficient way.  RMDs are still 4 years away. This was a good exercise to get a feel of how my demise would impact my wife’s finances. It would have some financial impacts, but I believe our plan can handle them. I’m considering running some more detailed projections varying the age at death to assess the impacts, but a quick look made me reasonably confident our retirement savings will be adequate, even considering long term care. I will also continue to look at Roth conversions each year.   Richard Connor is a semi-retired aerospace engineer with a keen interest in finance. He enjoys a wide variety of other interests, including chasing grandkids, space, sports, travel, winemaking and reading. Follow Rick on Twitter @RConnor609 and check out his earlier articles.
Read more »

Investing

Financial Lessons

WHAT'S THE MOST important idea in personal finance? It’s hard to single out just one, but over the years, I’ve found the following dozen ideas to be among the most useful.
  1. Whether it’s on TV or online, there’s never any shortage of market prognosticators. Especially during a bull market, everyone seems to have an opinion on where things are headed. The reality, though, is that people can only guess about how the economy, the market or any individual investment will perform. Convincing as they might sound, no one has a crystal ball. That’s why, when it comes to investing, I suggest taking an evidence-based approach, one that relies as much as possible on data and research rather than on the simple stories, anecdotes and sayings that are so prevalent among market commentators.
  2. What does the data tell us? Among the most significant research in recent years is the work of Hendrik Bessembinder. In looking at the historical returns of stocks, he found that just a tiny fraction—only 4%—have accounted for the vast majority of the market’s gains over and above what Treasury bills paid, and the median stock actually delivered a negative return. This is one of the key reasons I recommend index funds rather than picking individual stocks or investing in an actively-managed fund. Identifying that 4% is almost impossibly difficult. But if you invest in a broad-based index fund, you’ll have a high likelihood of owning the next Apple or Nvidia.
  3. Be careful not to miss the forest for the trees. The most important driver of investment risk and return for most people, most of the time, is asset allocation. In other words, the dollars you have in stocks vs. in bonds or in cash will almost always be the most consequential decision. It’s easy to lose sight of that, though, because so much of the investment commentary from day to day focuses on details like small differences in fund expenses or small differences in bond yields. To be sure, details can be important, but only after considering the big picture.
  4. Another challenge in investing is that certain rules of thumb gain so much popularity that they end up being seen as rules rather than just guidelines. For example, some say that the percentage of a portfolio allocated to bonds should be equal to an investor’s age. To me, that’s illogical. Consider Bill Gates. He’s 70 years old, but it stands to reason that he shouldn’t have the same asset allocation as any other 70-year-old. Rules of thumb are useful as points of reference, but we shouldn’t lose sight of the fact that everyone’s situation is different, and our investments should reflect that. More to the point, don’t worry if you’re doing something different from the next person.
  5. Buy insurance, but only to protect against losses you couldn’t absorb on your own. What does this mean in practice? In many cases, it’s possible to significantly cut insurance premiums by increasing deductibles. For example, if you have a seven-figure net worth, you might consider raising the deductible on your homeowner’s insurance to $5,000 or $10,000 or even more. Similarly, you might re-evaluate your life insurance as your net worth grows. You’ll likely become “self-insured” at some point, and then you could reduce or drop that coverage.
  6. Personal finance is quantitative, but we should never make decisions based only on the numbers. For example, a common question is how much cash to keep on hand. While we could work out an optimal number on a calculator, that shouldn’t be the final answer. You should also consider what would provide you with peace of mind. That is equally important.
  7. Be wary of the psychological pitfall known as recency bias. This is the tendency to extrapolate from recent experience and to downplay the possibility that things might change. The most famous example? In the late-1920s, when the stock market was booming, Yale University economist Irving Fisher declared that the stock market had reached a “permanently high plateau.” Just nine days later, the market crashed, ultimately dropping 89% from its peak.
  8. Avoid high fees. The research firm Morningstar once wrote, “If there’s anything in the whole world of mutual funds that you can take to the bank, it’s that expense ratios help you make better decisions. In every single time period and data point tested, low-cost funds beat high-cost funds.”
  9. Keep things simple. Most importantly, I would be wary of investments that aren’t easily understood. Not only can this help keep investment costs down, but it also makes it much easier to monitor your financial picture. Legendary fund manager Peter Lynch said it best: “Never invest in any idea you can't illustrate with a crayon.”
  10. Avoid “interesting” investments. So far this year, Wall Street has introduced more than 1,000 new exchange-traded funds (ETFs). How many of these are worth your attention? My guess is you could probably count them on one hand. More than 80% of these new funds are actively-managed, and more than 30% employ leverage. And there are more to come. Fund companies recently filed paperwork to create ETFs that will track the performance of major league sports teams. They won’t actually own shares in the teams; instead, they’re expected to rise and fall in response to each team’s wins and losses.
  11. For years, I’ve argued that bitcoin isn’t a valid investment. Even though it’s gone way up since I first made that argument, I still feel the same way, and for the same reason: because it lacks intrinsic value. Unlike stocks or bonds, it doesn’t generate any dividends or interest. Bitcoin’s price is not anchored to anything measurable or tangible, and that’s why, in my opinion, its price is so volatile.
  12. When it comes to investment risk, investors’ attention usually turns to the stock market. That makes sense, but as we’ve seen this year, bonds are not without risk. And unfortunately, the total-bond market index, which is often seen as the simplest, set-it-and-forget-it option, is one that carries quite a bit of risk. If you’re choosing bond investments, my recommendation is to pay attention to a metric known as duration. This tells you how sensitive a bond, or bond fund, will be to interest rate changes. In my view, investors should hold a sizable portion of their bond investments in a fund, or in individual bonds, with a duration of less than two years.
Adam M. Grossman is the founder of Mayport, a fixed-fee wealth management firm. Sign up for Adam's Daily Ideas email, follow him on X @AdamMGrossman and check out his earlier articles.
Read more »

Behavior

The Art of Making Do

"Ed, I was caught like a naughty child beside that trash bin — in hindsight, it's quite an amusing image. As for your suspicion, you're entirely correct. There's real satisfaction in making do, not out of hardship, but as a lightly worn badge of honour to my frugal philosophy. On the matter of your garden fork, I took the opposite approach. Mine's a fine stainless steel piece, with the shaft and handle carved from a single piece of wood. It's a wonderful tool to look at, and I always enjoy handling it… the actual forking, less so."
- Mark Crothers
Read more »

Behavior

Time Is Priceless

"Mark, that’s an excellent point. We certainly don’t have to wait until retirement to recognize the value of our time. Looking back, I wish I had understood that as clearly as you did when your children were still at home. I spent too many years focused on building a business and providing for my family, sometimes at the expense of simply being present. I like your motto, “Use money, love people.” Money is a tool. The people we share our lives with are what give that tool a purpose. Thanks, Mark."
- Andrew Clements
Read more »

Free Newsletter

Get Educated

Manifesto

NO. 3: WE SHOULD focus relentlessly on what we want from our financial life. That’ll motivate us to save, drive our investment strategy—and help ensure we pursue the goals we care about most.

Truths

NO. 93: PAYING down a mortgage is often the best bond we can buy. We earn a return equal to the mortgage’s interest rate, which will typically be above the yield on high-quality corporate and government bonds. True, if we pay down a mortgage, we’ll have less mortgage interest to deduct—but that deduction is now less valuable, thanks to 2017’s tax law.

humans

NO. 53: WE FEAR spoiling our kids, and yet the next generation almost always seems spoiled because rising living standards mean our children typically live better than we did at their age. In fact, we may want to “spoil” our kids by giving them money and then nudging them to use it responsibly. Think of this as a trial run before they receive any inheritance.

act

EXPLORE EASING into retirement. Could you work fewer hours at your current job or switch to a new career that’ll carry you through your initial retirement years? By phasing into retirement, you can limit your portfolio withdrawals and put off claiming Social Security, while also giving yourself time to figure out what a fulfilling retirement might look like.

Savings Initiative

Manifesto

NO. 3: WE SHOULD focus relentlessly on what we want from our financial life. That’ll motivate us to save, drive our investment strategy—and help ensure we pursue the goals we care about most.

Spotlight: Family

The Jonathan I Found: Through Others’ Eyes

WHEN MY YOUNGER brother Jonathan died, I thought I knew who he was.
After all, we had shared a childhood in England, years together at boarding school, family adventures in Bangladesh, and more than six decades as brothers. I knew the journalist the world admired, the devoted husband and father, and the man whose words quietly helped millions of readers live richer lives, not simply financially, but personally as well.
I was wrong.
Over the past several months,

Read more »

The Boy Who Tried Hard: A Reflection

At ten years old, my twin brother and I stood in a dark hallway trying not to cry.
The suitcases had already been taken from the car. Around us stood other families saying goodbye to children far too young to understand why they were being left behind. Then suddenly it was our turn.
Two frightened boys clinging to their mother, tears streaming down our faces as we watched home disappear behind us.
“An ominous dark hallway,


Read more »

Children / grandchildren accounts

I saw a post on Bogleheads regarding a question on grandchildren accounts.. I haven’t set up an account there to post so here is a method we used when children were very young.
We started and gifted to gift-to-minor accounts.  Coordinate with the parents first so you don’t complicate financial aid packages for continued education.  Once the children had taxable wages we gifted to Roth accounts in their names.
We stuck with a balanced 100% equity,

Read more »

What would you do if you received this text from your child as I did this morning? 

“Hi. Could I borrow $5000? Only if you have it available from a cash source (don’t want to cause taxes for you). We depleted our HSA with all the medical expenses in the last year and still have bills to pay. I would need to start selling off stock and mutual funds at this point and pay the taxes on the earnings.”
I told him I would not loan him the money, but I would send the $5,000 immediately which I did.

Read more »

Throw, hit or kick … it all add$ up

If you have young children or grandchildren, you may know the answer to this question.
How much do families spend on their children’s sports activities? 🏈🏒🥍⚾️⚽️
The answer is a lot, often thousands of dollars a year. I know that from experience in our family. My children each spend four thousand more or less for their children’s equipment, team fees, travel costs and in some cases lessons.  
And then there are the fund raisers each team conducts.

Read more »

Tributes to Jonathan Clements

HUMBLEDOLLAR FOUNDER and longtime Wall Street Journal columnist Jonathan Clements passed away earlier this week. He was 62.
I reached out to several of Jonathan’s close friends and colleagues to ask for their remembrances. Taken together, they paint a picture of someone who was as beloved by his peers as he was by his readers.
As Jason Zweig put it, “I have just lost a friend, and so have you.”
Christine Benz,

Read more »

Spotlight: Southworth

Bucket List

WHEN YOU’VE BEEN saving and investing for a long time, you have a long list of things you wish you could do over. Like hanging on to Apple, instead of selling at $85 a share. Like buying an index fund, instead of that hot mutual fund that quickly turned cold. My wife calls these “what ifs.” We have a rule not to talk about them because they almost always lead to arguments about who was wrong. Of course, there are also “what ifs” on the positive side. What if we sold everything when the market crashed in 2000-02, 2007-09 and 2020? What if we hadn’t started saving in our 401(k) plans when we got married? What if I hadn’t chosen to leave corporate America to see the country in an RV and later entered seminary? My most positive “what if” these days is this: What if I hadn’t become a devotee of the bucket approach to retirement allocation in the past five years? Most of our negative financial “what ifs” happened when we forgot when we were going to need our money. Selling stocks or mutual funds just because they go up or down is foolish, especially when retirement is 10 or 20 years away. Kathleen and I were foolish a lot over the years, usually when the market boomed or busted. Discovering the bucket approach a few years ago has provided much more peace and financial serenity in our lives. We park two years of cash in certificates of deposit and savings accounts. Money for years three through seven goes into bonds and very-low risk mutual funds. Anything we won’t need for at least seven years is in stocks. Last year, when the stock market briefly crashed, I was—for the first time in my life—calm and serene because I…
Read more »

My Confession

I HAVE READ THAT confession is good for the soul. I suspect it’s also good for our financial health—or, at least, I hope so. I have a confession to make as a usually loyal fan, regular reader and occasional contributor to HumbleDollar. I’ve read less than a dozen of the site’s articles in 2022, and I’ve checked my portfolio just as infrequently. This is a new practice for me. I share it somewhat reluctantly because it may or may not be healthy. When I was a regularly practicing minister, it was rare when someone came to me to spill their darkest secrets. My religious tradition doesn’t require regular confession. When I counseled people in financial trouble, one of the first tasks I gave them was to write down everything they earn, spend, owe and own. In every case, I found that sharing honestly was not only good for the soul, but also for just about everything else in their life. Secrets and darkness often destroy; openness and sunlight give life. As I reflect on why I’ve disengaged from finances this year, I realize I’ve learned some good things—and some not-so-good things. I hope you’ll find a truth or two for yourself in my confession. Bad news isn’t fun and I avoid it. In years when the financial markets decline, I often stop looking at my portfolio. I do the opposite when the market is booming. Then I may check and recheck my balances multiple times a day. The bad news is that frequent checking sometimes led me to act impulsively. I’d sometimes sell low or buy during what I thought was a dip. I wish I was more like Warren Buffett, who famously advised, “Be fearful when others are greedy, and greedy when others are fearful.” Most of the time,…
Read more »

Santa Claus Rally

THERE ARE FEW certainties in life, but December always brings a few. Our neighbors will decorate their houses with bright lights, our mailbox will be stuffed with letters asking for charitable donations and the financial pundits will speculate whether there’ll be a Santa Claus rally this year. If you’re a regular reader of HumbleDollar, you know that a Santa Claus rally has the potential to fill our portfolios with extra dollars via higher stock and mutual fund prices. But the Santa Claus rally I want to share has been much more valuable to me than a few extra percentage points added to my net worth. I was in my early 20s and slowly putting my life back together after bankrupting myself with my compulsive gambling addiction. As the holidays came around, I began feeling lonely and even more depressed than usual. I had lost my money, my girlfriend and most of my self-esteem. A friend suggested I spend Thanksgiving delivering meals to seniors who couldn’t get out of the house. For at least one day, I forgot myself and felt good because of the smiles and joy my deliveries had brought. The Christmas season was going to be even harder. I’m the kind of guy who watches all the holiday movies and cartoons and can’t get enough of the spirit of giving. I decided to leverage my Thanksgiving learnings. I went to the costume shop and bought the most expensive Santa suit I could find. If I had a financial advisor back then, she would have warned against adding the equivalent of a week’s pay to my credit card debt. But more than 35 years later, I can say it was one of the best purchases I ever made. I soon became a volunteer in the Santa Claus helper patrol.…
Read more »

California On Our Minds

I just returned from a six-day silent retreat. What in the world could that have to do with retirement and financial life?  Maybe nothing or maybe a lot.  I’ve been going on silent retreats for more than 20 years, ever since I became a minister and they were part of my spiritual and professional development. These days in my semi-retired lifestyle they are still part of both. One of my goals for the retreat was to write a draft article about moving to California for Humble Dollar. As I wrote last year, we had the unexpected gift of our first grandchild being born in November 2023. We decided when we visited her last spring that we would leave North Carolina and move to the Bay Area in California, which was our home until 2001 and is where our son and his family live.  If you read articles about the best places to retire, North Carolina is near the top and California is near the bottom. Selling in California and buying - or even renting - in North Carolina makes smart financial sense. Doing it the other way? Not so much. We found a manufactured home last July that was in our price range and close to family. We made an offer below asking price. After some back and forth the seller said no. We soon found another home in the same neighborhood.  This time we made an offer above asking but we were outbid. The first home we had bid on ended up being sold for less than our offer!  We get daily real estate updates and went back to California in November to celebrate our granddaughter’s one year birthday and to look for houses all over Northern California.  We decided to wait for the next house that comes available…
Read more »

Return on Spending

WHEN I STARTED MY sales and marketing career, one of the first mantras I learned was, “You have to spend money to make money.” Salespeople like me would always be asking the company to spend more—on commissions, product development and support. The bean counters, as we called them, would always respond by telling us how tight the budget was and how we needed to cut expenses. Especially those expenses they didn’t think we needed, such as business travel and client lunches. When my roles changed over the years and I became responsible for the operations side of organizations, I came to appreciate more fully the plusses and minuses of spending money to make money. While I never overran an organizational budget in the three decades that I was responsible for them, I’ve also never fully left my sales self behind. When I led nonprofits, I often found myself trying to convince others that, to make money, we needed to spend money—on fundraising. But you don’t always have to spend money to make money. In fact, when investing, just the opposite is usually true. As mutual fund and exchange-traded fund expenses have plummeted, performance has improved. In investing, you get what you don’t pay for. What about spending money for expert advice on taxes, retirement planning and estate planning? That may indeed lead to more money—but not always. My computer knows that I’m interested in retirement and finances. I’m reminded of that because of the many brokerage firm, investment and get-rich-quick advertisements I see every day. These organizations clearly believe they need to spend money to make money—for themselves, not me—and, given the size of some of these organizations, they’re right. But before I click on these advertisements, I try to remember another famous mantra: A fool and his money are soon…
Read more »

Stuck in the Sand

MY WIFE AND I recently took our first mini-vacation since 2019. We traveled to the Outer Banks in North Carolina for a long weekend to celebrate our anniversary. The weather was perfect, the crowds were small, the food was delectable and the morning sunrise was spectacular. But none of these memories has stuck with me like the one that wasn’t so delightful. We spent a morning driving up the coast to enjoy the sights and sounds of the small villages and towns along the way, as well as the breathtaking vistas of the Atlantic Ocean. We were surprised when the two-lane road dead-ended on a beach. Four-wheel drive cars were invited to continue with hopes of seeing some of the wild horses who have roamed the beach for centuries. We own a four-wheel drive car, but I’d never driven on a beach before and my instincts were telling me, “Don’t do it.” We went ahead anyway. Within two minutes, we were stuck in the sand. Revving the engine and spinning the wheels made the situation worse, as did the non-loving words my wife and I exchanged. After finding no help in the owner’s manual, we got out to see what we could do. People driving by yelled, “Let the air out of the tires.” We got on our hands and knees to flatten out the sand around the wheels. We pushed special buttons in the car. Nothing worked. Eventually, someone stopped and offered to help push. I put the car in reverse and within minutes we were back on the road. The only wild horses we saw were on the postcards at the gift shop. But the experience hasn’t left me, probably because I often get metaphorically stuck in the sand. I’m guessing you do, too. Sometimes, it’s been in…
Read more »