FREE NEWSLETTER

EVERY DAY, I READ about the Federal Reserve’s thinking on interest rates—increase, hold, decrease—and the possible impact on the economy. But what about the impact on savers?
As someone who has most of his non-stock monies invested in taxable certificates of deposit, high-yield savings accounts and money market funds, I have a different criterion for the right interest rate: It’s the rate that would give me and other risk-averse savers a modest real return of perhaps 1% a year, after adjusting for inflation and taxes.
Unfortunately, after doing a few simple calculations, I’ve realized that notching this seemingly modest real return requires a rare combination of interest rates, tax rates and inflation rates.
Suppose a couple has “moderate” income—meaning 2023 taxable federal income between $89,450 and $190,750—which puts them in a 22% marginal federal tax rate. If we add an assumed 3% marginal state tax rate, that gives them a 25% total marginal rate. As shown in the table below, our hypothetical couple would achieve a 1% real return if they earned 4% interest with 2% inflation. Think of that as the “Goldilocks” scenario.
By contrast, with a 1% interest rate and 2% inflation—which was fairly typical pre-pandemic—the real return was quite negative. Hoping higher interest rates will drive that 1% real return? They won’t help if they’re accompanied by correspondingly higher inflation rates, plus taxes are assessed on the nominal interest earned, not inflation-adjusted interest earnings.

Yes, it’s better to have more income than less. Still, with a lower income, your chances of making a 1% or better real return on savings are higher because your marginal tax rate might be just 15%. This 15% assumes a couple has 2023 taxable federal income between $22,000 and $89,450, which would then be assessed at a 12% marginal federal rate, with maybe a 3% state tax rate on top of that.

On the other hand, if you’re fortunate to earn enough to reach the highest marginal tax rates, your chances of earning a 1% real return on savings are pretty low. This is due to a marginal tax rate of 45%-plus. Where does that figure come from? A couple with 2023 taxable federal income of more than $693,750 would face a marginal federal rate of 37%, plus a Medicare investment income surtax of 3.8%, plus an assumed state tax rate of 4%-plus.
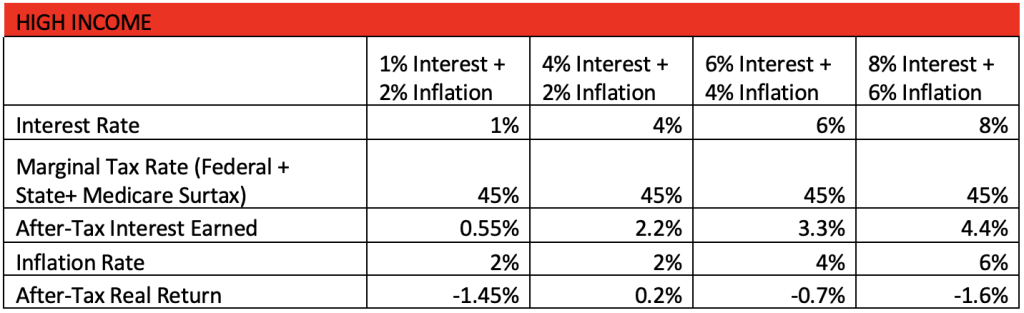
The lesson: While everyone’s circumstances differ, in general it takes a decent rate of interest, coupled with a low tax rate and a low inflation rate, to earn a real return on low-risk taxable savings. That doesn’t mean you shouldn’t hold cash investments for upcoming expenses and financial emergencies. But you won’t get rich holding your long-term investment money in cash.
 After 40 years working for GSK Consumer Healthcare (now called Haleon), Paul Sklar took advantage of a severance opportunity and left the firm in 2022. He now does part-time consulting as Paul Sklar Consulting LLC. In his spare time, Paul likes to exercise, read and spend time with his adult children.
Want to receive our weekly newsletter? Sign up now. How about our daily alert about the site's latest posts? Join the list.
Remember, when you pay down the mortgage by adding extra dollars, say monthly so you can pay it off early, you are in effect stuffing money in your walls. A house you live in is not an investment. It’s a place to raise the family and place of comfort and serenity.
Last time I looked I couldn’t sell the bathroom for a Viking River Cruise or sell the basement for the granddaughter’s education at SMU.
I love running a hypothetical using the S&P 500, or a a few funds we have had for decades, with the $400 a month extra going to the prepayment of the 30-year mortgage. Rolling 30-year periods starting in 1937 shows what $400 initial and the same monthly for 30-years yields in total return.
Investing in the greatest companies in the world has proven to be a fabulous place to create wealth. But, you time, patience, and discipline.
So true and so unfortunate!
After reading this article, I was wondering how/if you achieved a real return of 1% in the years before Covid when the Fed rates were zero?
I remember the days when the Prime rate was 21%, and MMFs were paying 15% and inflation was almost 15%. We weren’t making 1% on cash then either and tax rates were much